Cobb-Douglas Production Function and Neoclassical Growth Model

Cobb-Douglas Production Function and Neoclassical Growth Model

This is another code-less blog post in my "Coding Towards CFA" series. The concepts of the Cobb-Douglas Production Function and the Neoclassical Growth Model are too important to skip, which is essential for building a strong foundation in economics and of course for pass on the CFA exam. Neoclassical growth theory is a framework for understanding economic growth, analysing how the … Continue reading Cobb-Douglas Production Function and Neoclassical Growth Model

FX Carry Trade

FX Carry Trade

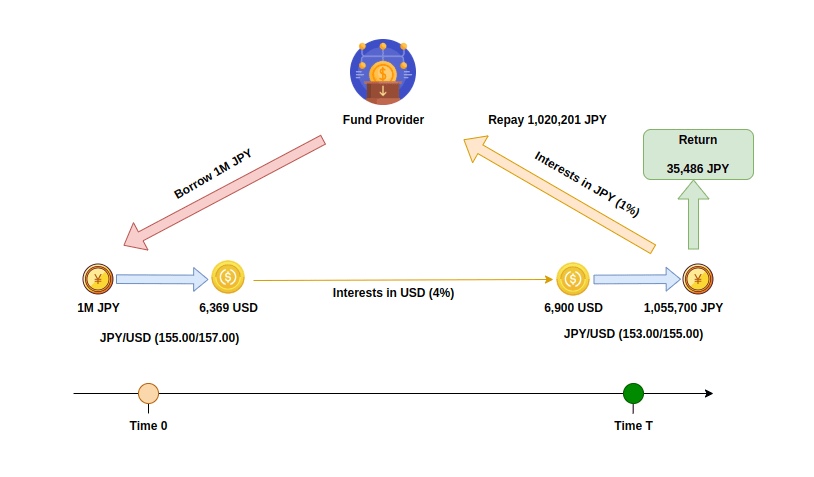
As discussed in the previous blog post, under the Uncovered Interest Rate Parity condition, the expected change in the exchange rate between two currencies should theoretically offset the interest rate differential between them. This would eliminate any opportunity for investors to profit from interest rate differentials. Fortunately, in the real world, uncovered Interest Rate Parity … Continue reading FX Carry Trade

International Parity Conditions

International Parity Conditions

This is the first code-less blog post in my Coding Towards CFA series. I’ve included this topic because of the importance of International Parity Conditions, which form the theoretical foundation of forex trading. These conditions are essential for gaining a deep understanding of equilibrium pricing, enabling investors to navigate the FX market more effectively. One of the main … Continue reading International Parity Conditions

Mark-to-Market of Forex Forward Contract

Mark-to-Market of Forex Forward Contract

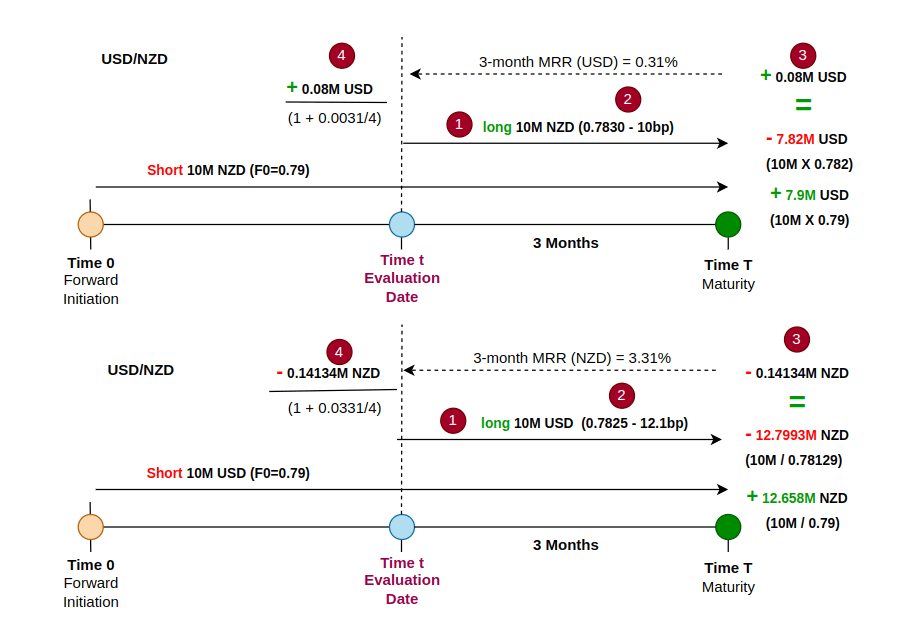
Mark-to-Market (MTM) is the process of valuing an asset, liability, or financial instrument, such as a forex forward contract, at its current market price rather than its book value or historical cost. The calculated MTM value represents the profit or loss that would be realised if the contract were settled at the current market exchange … Continue reading Mark-to-Market of Forex Forward Contract

Triangular Arbitrage in Forex Trading

Triangular Arbitrage in Forex Trading

Triangular arbitrage is a strategy used to exploit inefficiencies in the currency markets by executing a series of trades across three currencies in different markets. Let’s assume we now observe the following quotes for currency pairs from the interbank market and dealers. We want to analyse whether there is any arbitrage opportunity. Interbank Market Quotes … Continue reading Triangular Arbitrage in Forex Trading

Performance Attribution with Brinson Model in DolphinDB and Python

Performance Attribution with Brinson Model in DolphinDB and Python

Performance attribution is discussed in the CFA Portfolio Management curriculum, specifically in Module 2, Section 2: "Active Management and Value Added". Performance attribution is a process used to decompose the "value added," i.e., the excess return relative to a benchmark, into different sources. In the CFA curriculum, a simplified Brinson model is presented, which discusses the basic calculations of … Continue reading Performance Attribution with Brinson Model in DolphinDB and Python

The Monte Carlo Method of VaR Estimation

The Monte Carlo Method of VaR Estimation

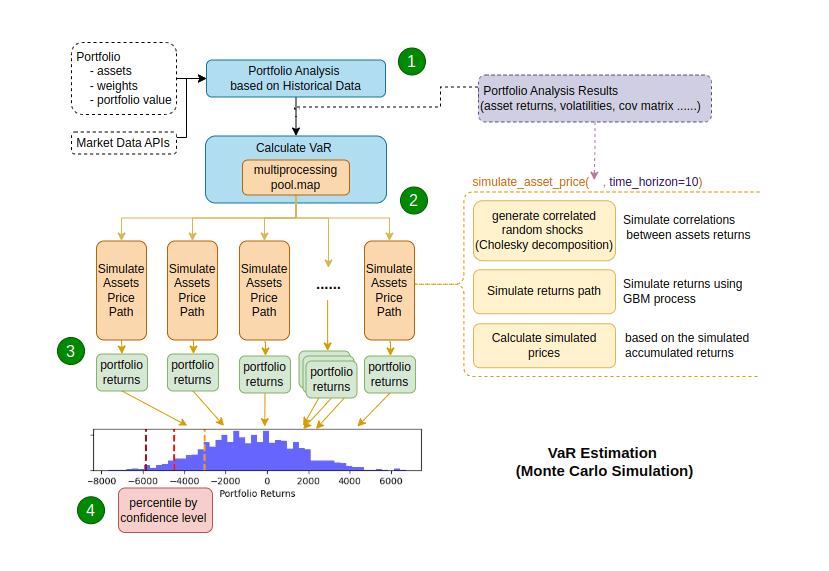
In the previous blog post, we explored the Parametric Method for estimating Value at Risk (VaR). While the parametric method offers the advantage of optimal computational efficiency, it relies on strict assumptions, particularly that returns follow a specific distribution (e.g., normal distribution). For complex portfolios, nonlinear instruments, and scenarios where flexibility and precision are critical, the parametric method may not be suitable. In such … Continue reading The Monte Carlo Method of VaR Estimation

The Parametric Method of VaR Estimation

The Parametric Method of VaR Estimation

In the previous blog post, we explored the Historical Method of VaR Estimation. The historical method is simple and intuitive; however, it relies on the assumption that financial markets will repeat historical patterns, disregarding structural changes in market conditions. This limitation makes the historical method less practical in real-world scenarios. In this blog post, I will … Continue reading The Parametric Method of VaR Estimation

VaR Overview and the Historical Method

VaR Overview and the Historical Method

Value at Risk (VaR) is arguably the most widely used metric for risk management. It quantifies the potential loss in the value of a portfolio over a certain period. In this blog post, I will first provide an overview of VaR, clarifying its definition and discussing its advantages and disadvantages. Then, I will implement Python code … Continue reading VaR Overview and the Historical Method

Setup QuantLib C++ Dev Environment with VS Code on Linux

Setup QuantLib C++ Dev Environment with VS Code on Linux

Since I really don't want to go back to Windows, the bulky, messy headache, I decided to set up my QuantLib C++ development environment on Ubuntu. It took a few extra steps compared to setting up Visual Studio on Windows, so I’m sharing the process in this blog post in case it helps anyone. Step … Continue reading Setup QuantLib C++ Dev Environment with VS Code on Linux